
BC First-Time Home Buyer Programs and Incentives
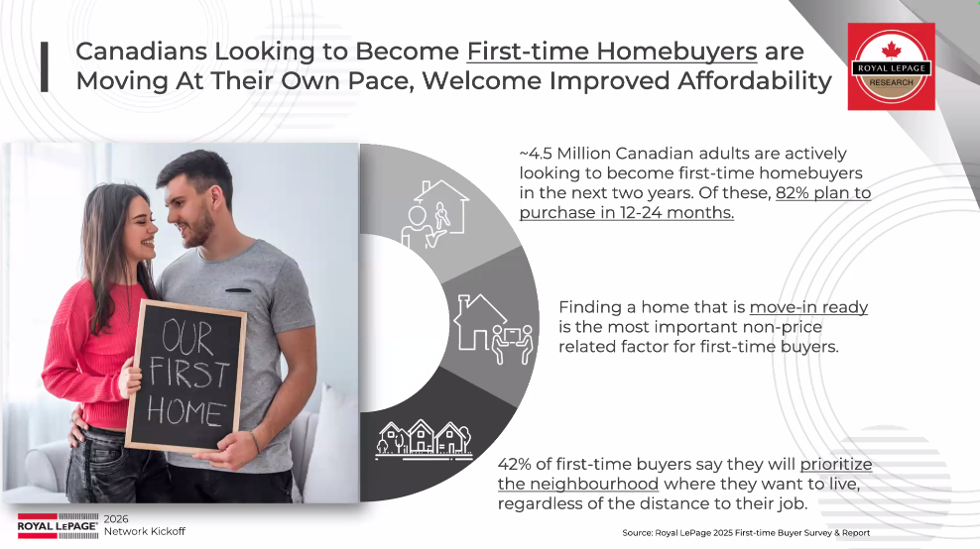
First-time buyers in Coquitlam, Port Moody, Port Coquitlam and across Greater Vancouver have access to several government programs that may significantly reduce upfront costs and improve overall purchase strategy. Understanding how these incentives interact with local pricing, presale opportunities and mortgage qualification can make a meaningful difference when planning your first home purchase.
Buying your first home in British Columbia can be more affordable than many buyers realize. There are several federal and provincial first-time home buyer programs designed to reduce upfront costs, lower taxes, and help you use savings more effectively. From registered savings plans and tax credits to Property Transfer Tax exemptions and rebates on new homes, understanding which programs apply to your situation can make a meaningful difference. Below is a clear breakdown of the first-time buyer incentives available in BC, how they work, and where to find official eligibility details.
Quick answer: most first-time buyers in BC can combine several programs. Save your down payment in a First Home Savings Account (FHSA) and/or withdraw from your RRSP with the Home Buyers’ Plan; pay little or no Property Transfer Tax through the BC First Time Home Buyers’ Program (or the Newly Built Home Exemption on a new home); claim the federal first-time home buyers’ tax credit; and, on a newly built home, get up to $50,000 back with the federal first-time buyers’ GST rebate.
Most first-time buyers in Greater Vancouver can combine programs to access:
Up to $8,000 a year ($40,000 lifetime) in tax-deductible FHSA savings
Up to $60,000 from your RRSP with the Home Buyers’ Plan ($120,000 for a couple)
Up to $50,000 GST rebate on a new home (full rebate up to $1 million)
Property Transfer Tax savings of up to $8,000 (homes up to $835,000)
A federal tax credit worth up to $1,400 (2026)
See how these apply to your situation!
Step 1 of 2
Thinking About Buying Your First Home?
Get the Home Hunter's Playbook
A practical guide to financing, finding the right property, making an offer, purchase costs, and the complete path to homeownership.
- ✓ Understand the buying process
- ✓ Prepare for financing
- ✓ Learn how offers work
- ✓ Understand purchase costs
Step 2 of 2
Almost done
Add your phone number and a few optional details so I can send you information relevant to where you are in your home search.
Your Playbook is ready
I've also sent you the Home Hunter's Playbook by email. You can open it immediately below.
OPEN HOME HUNTER'S PLAYBOOK →
Federal First-Time Home Buyer Programs in Canada
First Home Savings Account (FHSA)
A First Home Savings Account (FHSA) is a registered plan that allows first-time home buyers to save for their first home tax-free, up to program limits. It combines two key benefits, contributions are generally tax deductible like an RRSP, and qualifying withdrawals for a first home purchase are tax free like a TFSA. You can contribute up to $8,000 a year, to a lifetime maximum of $40,000, and unused room carries forward (up to $8,000 extra in a later year). The account can stay open for up to 15 years. To open one you must be a resident of Canada, at least 18 (in BC, most financial institutions require you to be 19), and a first-time home buyer. This account is especially useful for buyers planning a purchase several years out.
First-Time Home Buyers' Tax Credit (HBTC)
This federal credit helps first-time buyers recover some of the costs associated with purchasing a home, including legal fees, inspections, and other closing expenses. The First-Time Home Buyers’ Tax Credit (the “home buyers’ amount”) is a non-refundable credit on $10,000, calculated at the lowest federal tax rate. With that rate now 14%, it is worth up to $1,400 for 2026 (it was $1,500 when the rate was 15%). If you buy with a spouse or partner, the $10,000 is shared between you, not doubled. While it does not provide cash at closing, it can reduce income tax payable after the purchase.
Details on the First-Time Home Buyers’ Tax Credit.
Home Buyers' Plan (HBP)
The Home Buyers' Plan allows first-time home buyers to withdraw funds from their Registered Retirement Savings Plan (RRSP) to help purchase a home. You may withdraw up to $60,000 in a single calendar year, or up to $120,000 combined if purchasing with a partner. These withdrawals are treated as a loan from your RRSP and must be repaid over a period of up to 15 years to avoid tax consequences. Repayments normally start in the second year after your withdrawal; if your first withdrawal was made between 2022 and 2025, they start in the fifth year instead. The federal government has proposed extending that longer grace period to withdrawals made up to the end of 2028, but that proposal is not law yet. This program can reduce the amount of cash required for your down payment.
Check to see if you qualify for the Home Buyers’ Plan.
GST New Housing Rebate
You may be eligible for a rebate on a portion of the GST paid when purchasing or constructing a new home, or when substantially renovating an existing home. This rebate may also apply when building an addition or converting a non-residential property into a residential home. Under the standard GST New Housing Rebate rules, the maximum rebate is $6,300. The full rebate applies to homes under $350,000 and it is phased out completely at $450,000, so in Greater Vancouver it rarely applies to new homes.
Check eligibility for the GST New Housing Rebate.
First-Time Home Buyer GST Relief on New Homes
A separate federal rebate for first-time buyers of new homes became law in March 2026. It removes the 5% GST (or the federal part of the HST) on newly built or substantially renovated homes valued up to $1,000,000, a saving of up to $50,000. For homes priced between $1,000,000 and $1,500,000 the rebate is reduced on a sliding scale, and homes above $1,500,000 do not qualify. Resale homes do not qualify because no GST is charged on them.
To qualify, you must sign the agreement of purchase and sale with the builder on or after March 20, 2025 and before 2031; construction must start before 2031 and be substantially completed before 2036. You must be at least 18, a Canadian citizen or permanent resident, the first person to live in the home as your primary residence, and you must not have lived in a home that you or your spouse or partner owned at any time in the current year or the previous four calendar years.
This rebate is separate from the standard GST/HST New Housing Rebate that applies to lower price thresholds. Where both programs apply, the first-time buyer rebate may effectively act as a top-up. Because eligibility rules, contract timing and occupancy requirements are important, buyers should confirm program details before relying on this incentive.
Read the CRA first-time home buyer GST/HST rebate details.
BC First-Time Home Buyer Programs and Property Tax Savings
BC First Time Home Buyers’ Program
Eligible first-time buyers in British Columbia may qualify for a full or partial exemption from Property Transfer Tax (PTT). For properties with a fair market value under $835,000, PTT is not payable on the first $500,000 and is payable only on the portion above that amount. This can result in savings of up to $8,000. Properties with a fair market value between $835,000 and $860,000 may qualify for a partial exemption. Homes above $860,000 do not qualify.
To qualify you must be a Canadian citizen or permanent resident, have lived in BC for the 12 months before the purchase registers (or filed at least two BC income tax returns in the last six years), never have owned a home you lived in anywhere in the world, move in within 92 days and live there for at least the first year. The property must be 0.5 hectares (1.24 acres) or smaller.
BC First Time Home Buyers’ Program eligibility details.
Home Owner Grant
The BC Home Owner Grant can reduce the annual property taxes payable on your principal residence. While not limited to first-time buyers, it can reduce ongoing ownership costs. The regular grant is up to $570 a year (seniors, veterans and people with disabilities may get more). The extra $200 grant for northern and rural areas ends in 2027, after which $570 applies across BC. For 2026, the full grant is available on homes assessed at $2,075,000 or less and is reduced above that. You must claim it each year when you pay your property taxes.
Home Owner Grant eligibility information.
Newly Built Home Exemption
Buyers of newly built homes in British Columbia may qualify for the Newly Built Home Exemption, which can reduce or eliminate Property Transfer Tax on homes valued at $1,100,000 or less. A partial exemption is available for properties slightly above this threshold, with the exemption fully phased out once the fair market value exceeds $1,150,000.
Newly Built Home Exemption details.
Who Qualifies as a First-Time Home Buyer
The BC and federal programs use different definitions, and this is one of the most common points of confusion:
- BC Property Transfer Tax exemption: you must never have owned a home that was your principal residence, anywhere in the world, and never have used the exemption before.
- Federal programs (FHSA, Home Buyers’ Plan, tax credit, GST rebate): generally, you must not have lived in a home that you or your spouse or partner owned in the current year or the previous four calendar years. So someone who sold a home several years ago may qualify federally but not for the BC exemption.
Each program has its own details, so confirm eligibility with the official links above before relying on any incentive.
How Much Can First-Time Buyers Save
Depending on purchase price, property type, and eligibility, first-time buyers in British Columbia may save thousands, and in some cases tens of thousands of dollars, through a combination of the FHSA, Home Buyers’ Plan, federal tax credits, BC Property Transfer Tax exemptions, and rebates available on qualifying newly built homes.
Two examples for a single first-time buyer who qualifies for every program (2026 rules):
- $650,000 resale condo: Property Transfer Tax would normally be $11,000 (1% on the first $200,000, 2% on the rest). With the first-time buyer exemption it drops to $3,000, a saving of $8,000. The tax credit returns up to $1,400 at tax time. There is no GST on a resale home, so the GST rebate does not apply. The down payment can come from an FHSA (up to $40,000 plus growth) and the Home Buyers’ Plan (up to $60,000).
- $800,000 newly built condo: the first-time buyers’ GST rebate removes the $40,000 of GST, and the Newly Built Home Exemption removes the $14,000 of Property Transfer Tax. With the $1,400 tax credit, that is about $55,400 in savings, before any tax deductions from FHSA contributions.
Actual savings depend on your price, timing and eligibility. When layered together, these programs can materially change affordability calculations and purchase timing decisions.
Sources: Canada Revenue Agency (FHSA, Home Buyers’ Plan, First-Time Home Buyers’ Tax Credit, GST/HST rebates); Government of Canada, Bill C-4 (Royal Assent March 12, 2026); Government of BC (Property Transfer Tax exemptions, Home Owner Grant). Reviewed October 2026.
Frequently Asked Questions for First-Time Home Buyers in BC
Can I use more than one first-time home buyer program?
Yes. Many programs can be combined, including the FHSA, Home Buyers’ Plan, federal tax credits, and eligible BC Property Transfer Tax exemptions.
Do first-time buyers pay Property Transfer Tax in BC?
Most first-time buyers pay little or none. With the First Time Home Buyers’ Program, there is no Property Transfer Tax on the first $500,000 of a home worth up to $835,000, a saving of up to $8,000; a partial exemption applies up to $860,000. Buyers of newly built homes may instead use the Newly Built Home Exemption, which covers homes up to $1,100,000.
Can first-time buyers purchase condos or townhomes?
Yes. Condos, townhomes, and detached homes can qualify if program requirements are met and the property will be your principal residence.
Is the First-Time Home Buyers’ Tax Credit paid at closing?
No. The credit is claimed when you file your income tax return and reduces tax payable after purchase. For 2026 it is worth up to $1,400 ($10,000 × the 14% lowest federal tax rate).
Does the Home Buyers’ Plan count as taxable income?
No, as long as you repay on schedule. If you miss a required annual repayment, that amount is added to your taxable income for the year.
Can first-time buyers get a GST rebate on a new home?
Yes, on a newly built or substantially renovated home (not a resale). The federal first-time home buyers’ GST rebate, in law since March 2026, removes the 5% GST on homes up to $1,000,000, a saving of up to $50,000, with a partial rebate up to $1,500,000. The agreement with the builder must be signed on or after March 20, 2025 and before 2031.
Eligibility rules and effective dates may change. Buyers should confirm current requirements before relying on this relief.
 The data relating to real estate on this website comes in part from the MLS® Reciprocity program of either the Greater Vancouver REALTORS® (GVR), the Fraser Valley Real Estate Board (FVREB) or the Chilliwack and District Real Estate Board (CADREB). Real estate listings held by participating real estate firms are marked with the MLS® logo and detailed information about the listing includes the name of the listing agent. This representation is based in whole or part on data generated by either the GVR, the FVREB or the CADREB which assumes no responsibility for its accuracy. The materials contained on this page may not be reproduced without the express written consent of either the GVR, the FVREB or the CADREB.