Vancouver Foreclosures & Court-Ordered Sales in BC
Properties in foreclosure can be a good way to source deals in real estate. It's important, however, to have a clear understanding of the foreclosure process before deciding to buy a foreclosure property, because a court-ordered sale works very differently from a regular purchase. For any specific questions about buying a Greater Vancouver foreclosure property, please don't hesitate to ask!
If your home is at risk of being foreclosed on, please review our avoid foreclosure section containing helpful information on how to prevent foreclosure. Interested in buying a Vancouver foreclosure? View a current list of properties in foreclosure.
What Is a Court-Ordered Sale in BC?
A court-ordered sale (often called a foreclosure sale) is the sale of a property under the supervision of the Supreme Court of British Columbia after the owner has defaulted on a mortgage. The lender, or another creditor, is given “conduct of sale” by the court, lists the property with a REALTOR®, and accepts an offer that only becomes binding once a judge or associate judge approves it in court.
- Who decides: the Supreme Court of BC. Every court-ordered sale must be approved by the court before it can complete.
- Redemption period: the owner usually gets six months to pay out the mortgage. The court can shorten or extend this.
- Your offer can be topped: other buyers can bring competing offers to the approval hearing, which can turn into a sealed-bid process.
- Sold “as is, where is”: no property disclosure statement and no warranties from the seller.
- Schedule A: every offer includes the lender's court-sale terms, which override the standard contract.
- Possession: if an occupant won't leave, removal requires a Writ of Possession and a court bailiff.
Understanding the Foreclosure Process in British Columbia
 In British Columbia, the foreclosure process involves several steps, including legal filings, court proceedings, and public listings. This guide walks you through each stage, from the basics of a court-ordered sale to how to place a successful offer. By familiarizing yourself with these procedures, you'll be better prepared to identify viable opportunities in the foreclosure market and to avoid the surprises that catch many first-time foreclosure buyers.
In British Columbia, the "foreclosure process" is referred to as the "judicial sale process". Foreclosure in BC is a court process: a lender can't simply take the property or sell it on its own. The petitioner or any of the respondents (i.e. 1st, 2nd or 3rd Mortgagee) can apply for a judicial sale, also known as a court-ordered sale (or more commonly known as a foreclosure), which will be carried out under the supervision of the court.
The judicial sale begins with a Demand Letter to the borrower, giving the borrower a short amount of time to pay out their mortgage. Then a petition is filed in the BC Supreme Court registry, and the borrower has 21 days to file a response. At the first hearing the lender asks for the Order Nisi, which fixes the time for redemption. The redemption period, usually six months, is the time period given to the borrower to redeem the mortgage, and the order also sets the amount required. The order nisi usually includes a personal judgment against the borrower for the amount owed. Where a lender (respondent) applies for such an order, he or she may satisfy the court that the value of the property is high enough to satisfy the costs of the sale and the claim of the petitioner. If the property is sold by judicial sale and the proceeds fall short, the petitioner is entitled to recover the difference between the sale proceeds and the mortgage debt from the borrower.
Once a petitioner or respondent has been granted conduct of sale, they act in the role of the vendor pursuant to the Court Order, only for purposes of disposition of the asset, and can now list the property for sale with a REALTOR®. From that point, the owner can no longer sell the property on their own.
When a party has expressed an interest in making an offer on a Vancouver foreclosure, their REALTOR® or the selling agent will draft an offer directed at the Vendor (usually one of the Mortgagees). At this point their REALTOR® should confirm that the purchaser understands that although they will be negotiating with the vendor and a deal may be agreed on, there is still a possibility that, when the offer is presented to the court, the offer may be subject to a sealed bid process by other purchasers. When making an offer on a Vancouver foreclosure you'll also need to agree to the following Schedule A. This document will be attached to your offer.
Once the offer is made and the terms are agreed to, the Purchaser commences their Subject Period. If the purchaser removes its subjects, the offer will be presented to court.
Steps in the BC Foreclosure Process
Every BC foreclosure moves through the same legal stages. The first four happen between the lender, the borrower and the court. A buyer usually enters the picture at stage 4, when the property is listed for sale, and the sale is only final at stage 5.
-
Lender
Demand Letter
A letter accelerating the loan and giving the borrower a short period of time to pay out the mortgage or bring the payments up to date, or else face foreclosure. Lenders usually send it after several missed payments.
-
Court
Petition
Filed in the B.C. Supreme Court registry. The lender is the petitioner, while the borrower and all other charge holders whose interests rank in priority behind the lender are the respondents. The borrower has 21 days to file a response.
-
Court
Order Nisi
The first order of the court. It establishes, amongst other things, the amount required to redeem the mortgage and the time period given to the borrower to redeem, usually six months. It normally also includes a personal judgment against the borrower.
-
Sale
Judicial Sale (Conduct of Sale)
The petitioner may choose to have the property listed for sale by the court. Unless special circumstances exist, the petitioner only seeks this order at the expiry of the Redemption Period (traditionally 6 months). Once conduct of sale is granted, the property is listed with a REALTOR® and buyers can make offers.
-
Court
Order Approving Sale
The court approves the sale of the property, often after hearing competing offers. Sale proceeds are paid out in order of priority (property taxes first, then the mortgages and other charges). If the sale proceeds do not pay the petitioner in full, the petitioner will seek the deficiency from the respondent borrower under a court action.
Alternative ending
Order Absolute of Foreclosure
If the redemption period has expired and if:
- the property is worth the same amount as the mortgage debt or more;
- the respondent borrower is judgment-proof (i.e., no assets or money to apply towards a deficiency); or
- there are no offers under a judicial sale;
the petitioner can seek an absolute order of foreclosure, under which the petitioner becomes the new registered owner and all respondents are wiped off title. No further action can be taken against the respondent borrower after the court has granted the order absolute. In practice, lenders seek an order absolute far less often than a court-ordered sale.
How Buying a Court-Ordered Sale Works, Step by Step
From a buyer's side, the process looks like this. The key difference from a normal purchase is step 5: your accepted offer still has to survive a court hearing.
- Find the property and do your homework. Court-ordered sales appear on MLS® like other listings. Ask your REALTOR® for recent comparable sales so you know what the property is really worth before you write an offer.
- Write an offer with Schedule A attached. The offer is directed to the lender acting as vendor. Schedule A sets out the court-sale terms and overrides the standard contract where they conflict.
- Negotiate and agree on terms. The lender's lawyer and listing agent will usually want the price supported by an appraisal or market evidence, because the court must be satisfied the price is fair.
- Complete your subject period. Arrange your inspection, financing, strata document review and legal advice now. Subjects must be removed before the offer goes to court.
- Attend the court approval hearing. The vendor's lawyer applies to have your offer approved. Other buyers can show up with competing offers on that day.
- Complete and take possession. If your offer is approved, the sale completes under a court order that clears the foreclosure parties' charges from title.
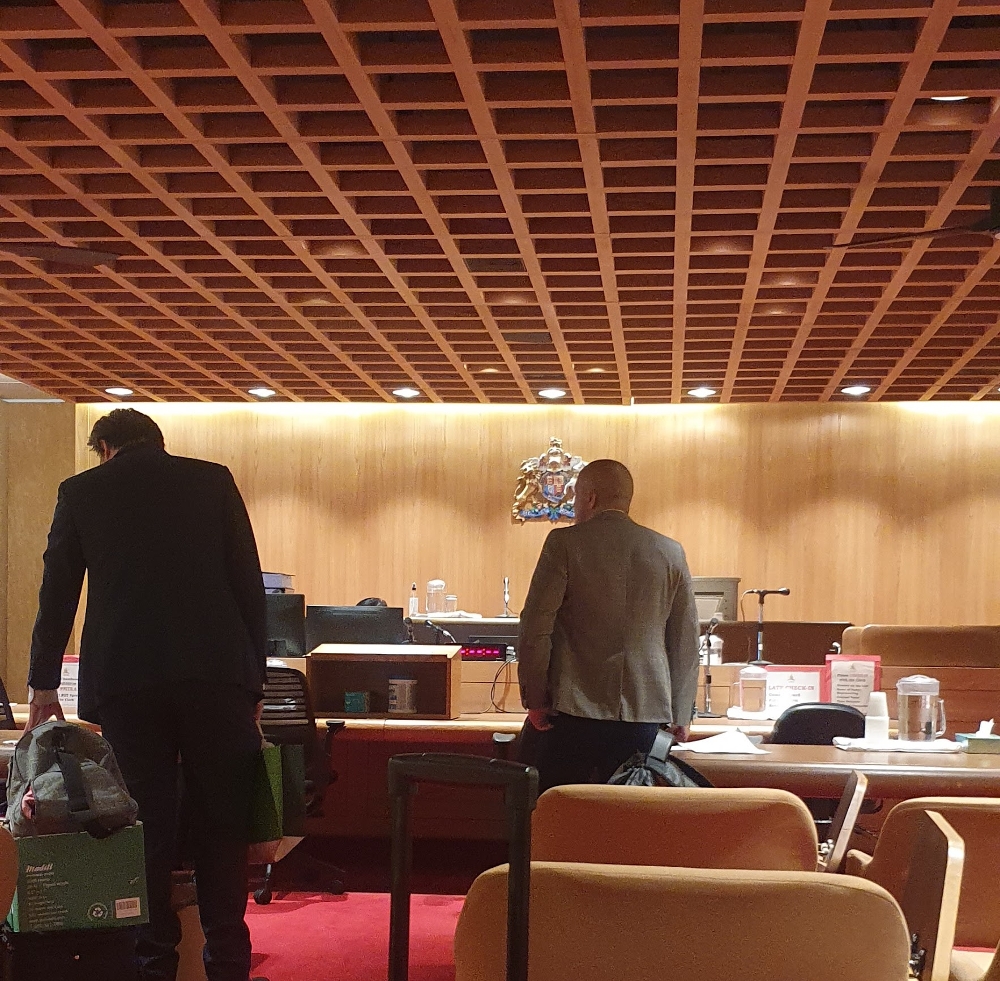
What Happens in Court
In the courtroom, the process works as follows:
-
1
The offer is presented
The vendor's lawyer presents the purchaser's offer to the judge or associate judge. (Associate judges were called “masters” until January 2024, and you may still hear the old term.)
-
2
Anyone else?
The court asks if there are any other parties in the courtroom who would also like to submit an offer. If there are not, and the appropriate marketing has taken place and the price of the offer is market value, the court will approve the sale.
-
3
Sealed bids, best deal wins
If there are competing offers in court, all parties, including the original purchaser, are instructed to leave the courtroom and resubmit their final offer in a sealed envelope to the vendor's lawyer. The court then reviews the offers and approves the best deal.
Important: if you have an accepted offer on a Vancouver foreclosure, there is always the possibility that another offer is accepted in court. Go to the hearing knowing the highest price you are prepared to pay, and have your deposit and financing ready so you can act on the day.
What Is in Schedule A?
Schedule A is the set of court-sale terms attached to every offer on a foreclosure. Your lawyer should review it before you sign, but these are the terms buyers most often ask about:
- Court approval is required. The seller accepts only as a party to the foreclosure, not as the owner, and the contract takes effect only once the court approves it. The court may hold a sealed-bid process among all bidders.
- “As is, where is.” There are no warranties or representations about the property's condition, including defects or water penetration, and no Property Disclosure Statement.
- No strata documents from the seller. For a condo or townhouse, the seller does not provide a Form B or Form F, so you need to obtain and review strata records yourself.
- The seller can withdraw. If the owner redeems or refinances the mortgage before approval, the sale can be cancelled without liability to the seller.
- Possession under a court order. If someone stays in the home, the seller's only duty is to apply for a Writ of Possession and instruct a bailiff.
- Time is of the essence. If you fail to complete on time, your deposit can be forfeited.
- GST is the buyer's responsibility where it applies, for example on a new or substantially renovated home.
Are Foreclosures in Vancouver Really a Bargain?
Sometimes, but not automatically. The court's job is to make sure the property is sold for fair market value, so lenders usually price court-ordered sales close to what an appraisal supports, and the court can refuse an offer that is too low. The opportunity is more often in the circumstances than in a deep discount: motivated sellers who want a clean, quick sale, properties that need work and scare off other buyers, and listings that sit while buyers are nervous about the court process.
The trade-offs are real. You buy as is, you may not get full access before you commit, the timeline is less predictable than a regular sale, and you can be outbid at the hearing after you have already paid for an inspection and legal advice. Factor those costs and risks into your price.
David's Take
Most of my foreclosure and court-ordered sale work has been on the buyer side, helping clients compete for these properties. The buyers who do best know the comparable sales cold, finish their due diligence quickly, and walk into court with a firm top number instead of getting caught up in a bidding war on the day.
Frequently Asked Questions on Foreclosures
What happens if the owner or tenant has not moved out by the possession date?
The biggest concern is that possession could be delayed. As the buyer, you cannot simply remove the owner or tenant yourself. Your lawyer would need to apply to the court for a Writ of Possession, which can involve additional time and legal costs.
Once issued, the Writ allows an authorized court bailiff to remove an occupant who refuses to leave. There is also some risk that an owner who knows they are being forced out could damage the property before leaving, which is something buyers need to be aware of when purchasing a foreclosure.
Are there additional risks if the registered owner is a non-resident of Canada?
Yes. The main concern relates to potential tax liabilities. In a foreclosure sale, the buyer may be required to indemnify the seller, usually the bank, for certain unpaid taxes connected to the property. Depending on the circumstances, this could include capital gains withholding requirements under section 116 of the Income Tax Act, BC's Speculation and Vacancy Tax, or Vancouver's Empty Homes Tax where applicable.
The challenge is that the bank may not know where the owner currently lives, how the property was being used, whether it was vacant, or whether non-resident tax requirements apply. Because of this, some of the risk can fall back on the buyer. Your lawyer should review this carefully and advise you on the appropriate due diligence before you proceed.
Can I make my offer subject to an inspection and financing?
Yes. Offers on court-ordered sales normally include subject conditions such as an inspection, financing and a review of strata documents. The difference is that all subjects must be removed before the offer is presented to the court, so plan to complete your due diligence quickly.
Can the owner stop the sale?
Until the court approves a sale, the owner can still pay out the mortgage, and Schedule A allows the seller to withdraw if that happens. After conduct of sale has been granted, the owner can no longer sell the property privately.
Do I need my own lawyer to buy a foreclosure?
Yes. The vendor's lawyer acts for the lender, not for you. Have your own lawyer or notary review Schedule A, the title and any tax issues before you remove subjects, and confirm who will attend the court hearing with you.
Can I flip a foreclosure property?
You can, but budget for tax. Since January 1, 2025, the BC home flipping tax applies to residential property sold within two years of purchase: 20% of the taxable profit if you sell within 365 days, decreasing to zero at 730 days, with some exemptions. Speak with your accountant before you buy.
Sources: People's Law School: If you're facing foreclosure · Clicklaw Wikibooks: Foreclosure · Courthouse Libraries BC: Associate Judges. This page is general information, not legal or tax advice.
Our Vancouver foreclosure listings are updated regularly to provide the latest investment opportunities. We offer a range of properties, from single-family homes to condos, suited for buyers looking for value and potential growth. Each listing includes essential details, making it easier for you to compare and make informed decisions.
To give you an idea of what to expect, we've compiled a sample of some of the properties currently in foreclosure. See below.
For a complete list of current Greater Vancouver foreclosures, please get in touch by completing the form below. An updated list of foreclosures will be emailed to you monthly.
Avoid Foreclosure
There are many reasons why a person might fall behind with their loan payments, such as a loss of employment, medical expenses and other life-altering events. As we all know, with debt comes a responsibility to make sure the debt is paid back to the lender on time. If it's not, our credit rating is affected, making it harder for us to buy things in the future.
Unlike credit cards (where it only hurts your credit rating), not paying your home loan on time may result in the lender foreclosing on and taking ownership of your home, or having the court order it sold.
If you are falling behind, contact your lender as soon as possible. Lenders generally would prefer not to foreclose, and will usually work with you to get you back on track. Never ignore the lender's letters or phone calls. The problem won't go away and foreclosure will more than likely be the result. I would also recommend getting legal advice from somebody who specializes in foreclosure and debt in BC and can properly assess your situation.
Your Options Before the Court Orders a Sale
- Bring the mortgage up to date. Paying the arrears by the deadline in the demand letter can stop the process before it reaches court.
- Refinance or pay out the mortgage. You can redeem the mortgage at any point during the redemption period, which is usually six months.
- Sell the home yourself. Until the court gives the lender conduct of sale, you can still list and sell on your own terms, which usually gets a better result than a court-ordered sale.
- Respond to the petition. You have 21 days to file a response once you are served. Missing that deadline lets the process move ahead without you.
- Get free or low-cost help. People's Law School explains the process and lists free legal advice clinics, and the non-profit Credit Counselling Society helps people dealing with debt.
Another option may be to sell your home pre-foreclosure, pay the lender from the sale proceeds and have a fresh start. If you decide to explore this route, I have literally hundreds of buyers who may be willing to buy right now. If you require a quick sale and information on what your home might sell for, please let us know, or request a free home evaluation. Everything you share is kept confidential.
Get Expert Guidance on Vancouver Foreclosures
If you are interested in exploring the Vancouver foreclosure market, reach out to us today to schedule a free consultation, or sign up for alerts to get the latest foreclosure listings straight to your inbox. Together, we can find the right investment opportunity for you.
Call or text 604-340-4400 · david@reimers.ca
 The data relating to real estate on this website comes in part from the MLS® Reciprocity program of either the Greater Vancouver REALTORS® (GVR), the Fraser Valley Real Estate Board (FVREB) or the Chilliwack and District Real Estate Board (CADREB). Real estate listings held by participating real estate firms are marked with the MLS® logo and detailed information about the listing includes the name of the listing agent. This representation is based in whole or part on data generated by either the GVR, the FVREB or the CADREB which assumes no responsibility for its accuracy. The materials contained on this page may not be reproduced without the express written consent of either the GVR, the FVREB or the CADREB.